Bank of Israel Tightens Rules on Parental Mortgage Co-Signing
The Bank of Israel restricted banks from counting more than half of parental income for mortgages where parents act as co-borrowers without property rights.
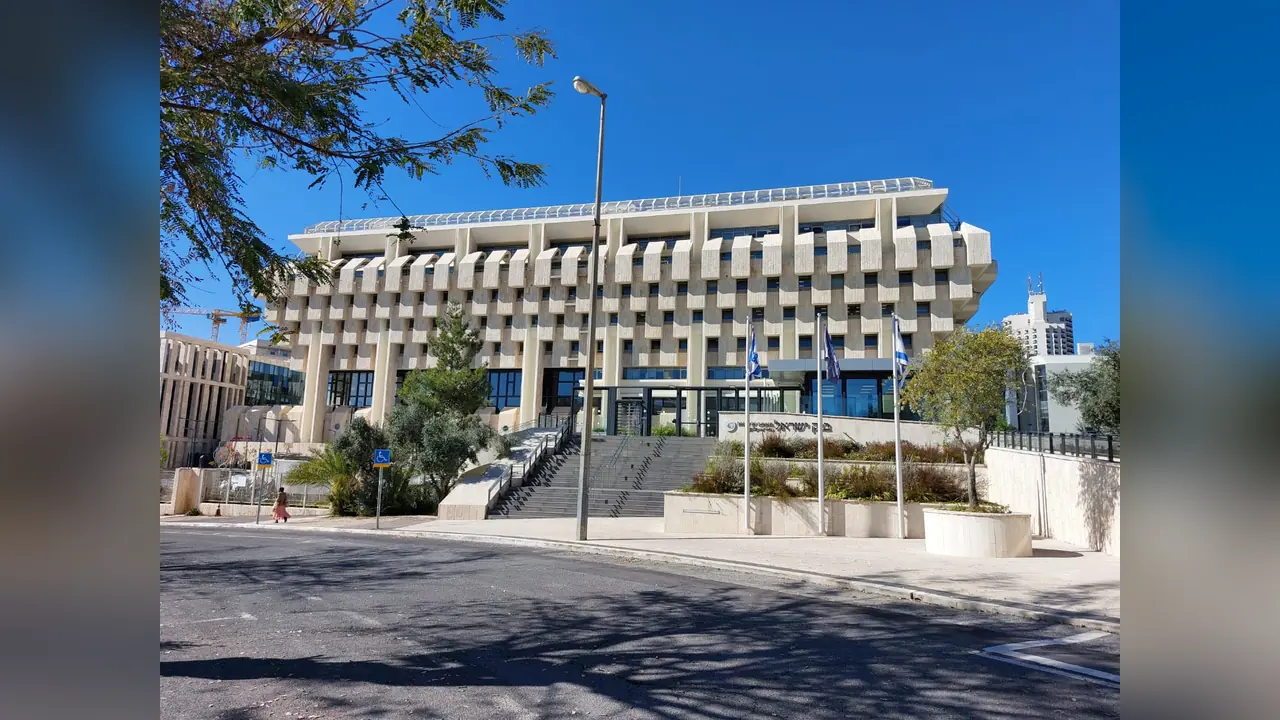
The Bank of Israel has issued a clarifying directive tightening restrictions on parental financial assistance for home purchases. In an updated Q&A document published on Monday, the Banking Supervision Department clarified that when a parent joins a mortgage as a co-borrower and pays the full monthly installment without holding property rights, the bank may account for no more than half of the parent's disposable income.
The clarification targets a common practice known as "borrower reversal," where parents step in to bolster their children's mortgage applications. This mechanism previously allowed banks to weigh a significant portion of parental income toward repayment capacity while the children's income was only partially considered.
Under Bank of Israel regulations, the monthly mortgage payment cannot exceed 50 percent of a borrower's disposable income, a metric known as the PTI ratio. In practice, banks must allocate higher capital reserves for PTI ratios exceeding 40 percent, increasing borrowing costs and raising the risk of application rejection. Consequently, a higher recognized income ceiling expands borrowing capacity.
The new guidance is expected to heavily impact young homebuyers with temporary lower incomes, such as early-career professionals, and winners of subsidized government housing programs where adding parents as property co-owners is restricted. Industry experts warn that while the measure aims to curb household credit risks, it effectively blocks viable borrowers who possess strong familial support networks and reliable repayment capabilities.