Bank of Israel Splits Growth Forecast: The Nvidia Factor in the Economy
The Bank of Israel split its growth forecast for the first time, distinguishing between overall output driven by giants like Nvidia and domestic economic activity.
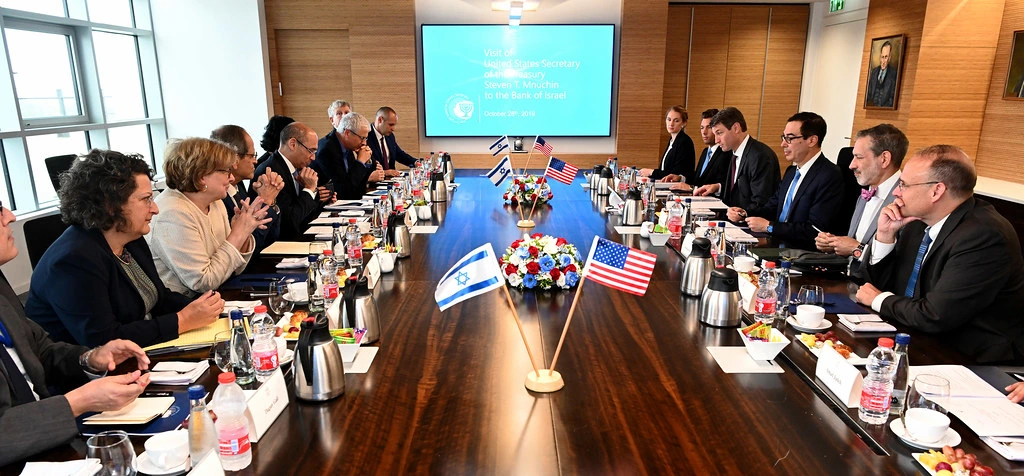
The Bank of Israel made history today by splitting its macroeconomic growth forecast for the first time: separating growth including the foreign manufacturing of Israeli companies from growth without it. Put simply, this means growth with Nvidia and without Nvidia. This is not a mere technical adjustment, but a clear statement from the central bank that two distinct economies are operating in Israel today, and only one truly reflects the daily reality of workers, consumers, and the labor market. Foreign manufacturing—goods developed locally but produced by overseas subcontractors without crossing physical borders—surged from 1.7% of GDP in 2023 to 3.5% in 2025, reaching 5.8% in the second quarter of 2026.
The Dual Growth Forecast
Official projections now point to overall growth of 5.6% in 2026 and 7.5% in 2027, figures well above recent IMF estimates. Yet excluding Nvidia, the numbers drop significantly to 3.4% and 5.1% for the same years. This single component contributes 2.2 and 2.4 percentage points, respectively, though the Bank of Israel admits an uncertainty margin of at least one percentage point in either direction. While every economist discusses artificial intelligence, predicting its precise trajectory remains impossible.
The divergence appears across every metric. Exports are projected to surge by 14% in 2026, but by just 5% without foreign production. Governor Amir Yaron and his team explicitly define the smaller figure as the one that "better represents domestic economic activity." The larger figure is not erased, as overseas production generates tax revenues that impact the deficit and public debt. However, it does not rely on local capital or Israeli labor, most profits flow to foreign shareholders, and taxes on these revenues are largely reduced.
Fiscal Implications and Political Context
In the accompanying charts, the curves diverge: GDP climbs alongside GNI, which reflects Israeli incomes, while domestic-only output lags behind. The fiscal impact is even sharper. The debt-to-GDP ratio is projected to fall from 68% at the end of 2026 to 66.5% by late 2027. However, discounting foreign manufacturing, the ratio actually rises from 70% to 70.5%, proving that the expected decline in national debt is largely the result of an inflated GDP numerator.
Meanwhile, Prime Minister Benjamin Netanyahu recently highlighted an IMF growth forecast of 4.5% under the banner of a booming economy. When questioned on the claim, Governor Yaron noted that countries at war typically lose about 10% of their GDP, placing Israel near its baseline trend in total output, though still 3.7% below it when excluding foreign production. Inflation remains anchored at 1.5%, and the risk premium is near pre-war levels.
"The credit belongs to the public and the firms," Governor Yaron stated, pointedly omitting the government from the engines of resilience.
With elections approaching, the central bank’s message is clear: the economy is surviving and outperforming expectations not because of government policy, but thanks to the resilience of citizens and enterprises navigating a protracted conflict.